01
The gap
Governance was built for humans, not agents.
Before you compare the markets, change the question. A site that scores perfectly for an AI training campus can be categorically wrong for an edge inference node, and the reverse. AI demand has fractured the market into four infrastructure archetypes, each with its own non-negotiable conditions. This is the lens to read every market in this report through.
The lens follows a framework developed with our advisory board: a workload-first, site-second discipline for matching what gets built to where it can actually run. It is contributed analysis, graded and sourced like the rest of the report.
Four ways to read a site before the markets are compared. Open any one, or take them in order.
The framework author, on the record
The workload-first, site-second framework this layer runs on was developed with Doug Mouton. Here is the reasoning underneath it, from thirty years of delivery and two hyperscalers. His argument is that most of what the industry treats as an engineering problem is a discipline problem, that the cost spread between operators building the same thing proves it, and that the binding constraint at the end of this decade will be neither power nor silicon but the people asked to build at a rate nobody has attempted. Nine files on how it actually gets built.
The standardisation argument is easier to agree with than to act on. He imposed that discipline with hyperscaler authority behind him, and whether a third-party developer competing for a lease could hold the same line is a different question, and one he was not asked.
His cost figures are recollection from the seat rather than a published series, and they describe the period he was running delivery. They are graded Contributed and are the numbers here most worth putting to a second source. The asymptotic-efficiency claim is his read rather than a measured finding, and it sits against a body of industry reporting that still claims material gains.
Contributed via interview with Entelligencia, 30 July 2026. The desk’s record is notes rather than transcript, so his positions appear as attributed summary and no sentence is set inside quotation marks. Direct quotation follows his review. His read on the United States runs in the USA chapter; the full conversation is A Roll Edition 04.
Every condition in this chapter, power, water, land, skills, resolves into the same question at the end of a programme: can the finished building be shown to do what it was designed to do. That is a separate discipline from construction, and the industry has historically bought it as a service near the end rather than a thread through the whole build. This contributed read sets out where risk is actually created, why the joins between phases matter more than the phases, and why the commissioning crunch will not be solved by hiring.
The lifecycle as one line. Almost all the risk is created at concept and design; in the conventional model the people who catch it are appointed at the end.
From high voltage crossing the fence to why extreme density cannot be fully proven before the accelerators are running.
Five patterns a verifier sees repeat. None of them look like a building falling over.
Contributed to The Next Hotspot via the Entelligencia briefing survey, attributed by name with firm and title at the contributor’s request. Views attributed to the author. The full read, including the lifecycle diagram and the findings dossier, is published as Mind the Gap.
Compute is the upper limit. Security governance is the lower one, and how high the first can go depends on how solidly the second is defended. This contributed brief reads the gap: identity systems built for humans rather than AI agents, the data hall itself as a physical cyber target, and why the market does not yet price security maturity. Open any file for the read.
This chapter treats cooling as a design choice. This seat treats it as a set of trade-offs that a hot, humid, land-constrained market forces earlier and harder. Singapore has now written a liquid cooling standard for tropical conditions, and the reason it exists is not that the technology was missing. Six files on what the standard actually fixes, where the density thresholds really sit, and the test that separates a genuinely adaptable building from an expensive one.
A water engineer’s read, contributed to The Next Hotspot
This layer treats power as the condition that binds. Alain Mestat scores water at 100 out of 100 as the next constraint, and then argues against the word constraint. Water is local, seasonal and political where power is a question of capacity, and a great deal of what the industry currently uses can be engineered away. Nine files, including the clearest account of what a data-centre water footprint actually contains that this desk has been given.
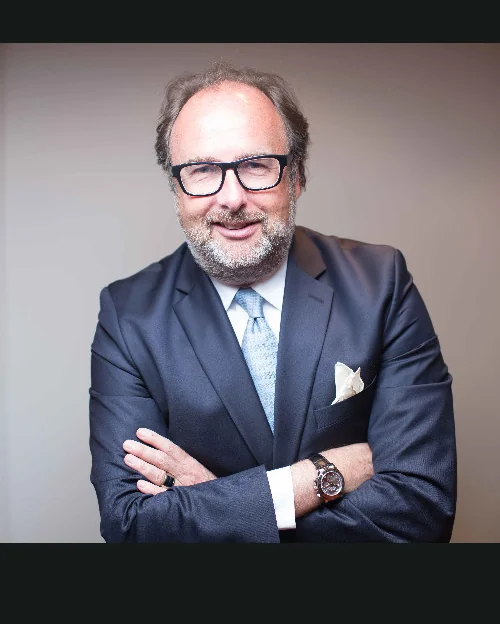
His correction to the framing this layer uses. Power is a question of securing sufficient continuous capacity. Water is local, seasonal and politically sensitive. A site can look viable on average annual availability and still fail on the hottest day, when the local network cannot meet peak cooling demand and the electricity system is under maximum pressure at the same moment.
In water-stressed regions where data centres compete with households, agriculture, energy generation and other industry, and especially where potable water is still used for evaporative cooling. The first constraint is not the cost of water. It is planning permission, connection capacity, abstraction rights, discharge restrictions and community acceptance.
“Power cannot be secured without considering water, and water cannot be managed without considering energy.”
The point this layer had not made. Thermal and nuclear generation depend on water for cooling; abstracting, treating and distributing water requires energy. In extreme heat and drought both systems come under pressure at once, precisely as cooling demand peaks.
It has several, which is why published figures vary so widely. An honest account separates water withdrawn from water evaporated and therefore consumed, from blowdown discharged, from water recovered and reused, and states the source: potable, reclaimed, surface or groundwater. A facility withdrawing a million cubic metres and returning most of it is a different thing from one consuming the same volume by evaporation, though returned water may come back warmer, more saline or carrying treatment chemicals.
The component most often omitted. The electricity a data centre consumes was generated somewhere, and thermal and nuclear plant withdraw and consume substantial water to cool. That indirect footprint should be calculated on actual consumption against the water intensity of the location and time-specific power mix, not a national annual average. A site with very low on-site water use can still carry a large off-site one.
The trade-off that follows. Eliminating on-site water through dry cooling raises electricity demand, and depending on how that electricity is generated, part of the water impact simply transfers from the facility to the utility supplying it. Optimising one resource in isolation moves the problem rather than solving it.
His worked illustration, and the reason WUE alone will not do. A 100 MW IT facility running continuously at a reported WUE of one litre per kilowatt-hour uses roughly 876,000 m³ a year inside that reporting boundary. Change the utilisation rate, the climate, the cooling technology or the accounting perimeter and the headline figure moves substantially.
Confusing withdrawal with consumption. Reporting design capacity rather than measured use. Counting only water used at the facility. Excluding the water used to generate the electricity. Using fleet-wide or annual averages that conceal local and seasonal pressure. Combining potable and reclaimed water without distinguishing them. Omitting peak summer demand, when cooling and scarcity coincide.
He scores water at 100 out of 100 as the next constraint and refuses to treat scarcity as fixed. A significant share of current industrial cooling demand can be engineered down through climate-sensitive cooling design, higher cycles of concentration, chemical-free treatment, blowdown recovery and reuse, reclaimed-water integration and hybrid cooling. The question is not technological possibility. It is whether operators, regulators and financiers make water efficiency a requirement from site selection onward rather than a reporting exercise afterwards.
Water treatment is his business, which is worth knowing while reading a case for water. It is also the reason the account is unusually specific: the taxonomy in file 04 is the kind of thing you only write if you have had to measure it.
The 100 out of 100 is the strongest framing score any contributor has given this report, and it is worth reading against his own answer, which spends most of its length arguing that the constraint is soluble. He is not saying water stops the build. He is saying it decides where the build goes, and that the industry is currently measuring it in a way that cannot support that decision.
The 876,000 cubic metre figure is his illustration on stated assumptions rather than an observed facility, and is graded Estimated. It is also the most useful number in this section, because it converts a WUE of one into something a planning authority can argue with.
Contributed via the Entelligencia briefing survey, 31 July 2026, attributed by name with firm and title at the contributor’s request. His positions are reported in the desk’s house style except where quotation marks appear. Claims describing engineering practice are his and are graded Contributed; the worked illustration is graded Estimated on his stated assumptions. Water also runs through Chile, Europe and The Wrong Numbers, and this file is the reference point for all three.
A water systems engineer’s read, contributed to The Next Hotspot
This layer has just heard that water is the limiting factor, scored at 100. Nico Verdonck reads it differently. He argues the problem is real but can vary greatly by region: acute in some regions, subordinate to power in most, and already in motion because regulation and operators’ own objectives are setting it in motion. He supplies the pumps and water treatment systems, which means he sees the locations where it was designed properly and the locations where it was not.
This chapter treats power as the binding condition. The contributor here sells the thing that answers it, and says the category has changed underneath the industry: standby generation is converging with prime power, and the interesting move is no longer technical but financial. His positions are reported as he gave them, and where he is describing his own company’s offer the claim is graded Contributed rather than Verified.
Standby is “no longer a discrete category”. As connection timelines stretch past what developers can wait for, on-site generation becomes the first option rather than the fallback, with standby integrated into the same energy station. Contributed
He describes funding models where standby is financed together with the prime power system rather than sitting on the customer’s balance sheet as a separate capital line. If that holds, on-site power stops being a capital decision and becomes a procurement one. Contributed
A few megawatts while you wait is easy. Hundreds of megawatts for years, in his words, “has to be built like a permanent infrastructure”. His answer is grid-ready from day one, so the site switches over cleanly when the connection lands instead of being rebuilt. Contributed
On what actually replaces diesel today: HVO is the near-term move, cutting emissions by up to 90% as a drop-in, with the caveat that only HVO100 is genuinely pure. Everything AVK installs is dual-fuel. Hydrogen sits further out. Contributed
AI racks swing load faster than plant designed for stable demand expects. Backup has to respond faster, tolerate sharper transients, and sit physically closer to the load rather than simply being larger. Contributed
Equipment can now take longer to arrive than the rest of the site takes to build. His answer is capacity agreements with vendors including Rolls-Royce, reserving production slots ahead of demand and passing guaranteed capacity through to customers. Contributed
An industrial engineer’s read, contributed to The Next Hotspot
This layer treats the building as the thing that changes. Alberto Carpita scores efficiency at 75 out of 100 toward still having room, and then says the room is not where the industry has been looking for it. The most efficient sites already run at 10 to 15 per cent overhead on top of the IT load. There is almost nothing left to win in the shell. Everything that remains is inside the servers: immersion cooling, optical interconnects, advanced chipsets and software. The first industrial supplier to sit for this report, from the company that makes the busbars.
Industry-average PUE fell hard for a decade and then flattened. Best-in-class operators sit close to the physical floor. Carpita’s argument is that the gap between the two lines is now the only shell-side prize left, and it is small compared with what is still available inside the IT load.
Five data points, eighteen years. The average fell 38 per cent between 2007 and 2014, then moved four hundredths in the decade that followed. Google reports a fleet-wide 1.09, Meta about 1.08, Microsoft about 1.16. Carpita’s 10 to 15 per cent overhead is the disclosed best-in-class figure, not an aspiration, which is precisely why he says the shell is done.
PUE has reached its physical limits, and with the best sites at 10 to 15 per cent overhead there is little left to take out of the shell. The room that remains is in the IT load itself: immersion cooling, optical interconnects, advanced chipsets and software optimisation, none of which has yet delivered its effectiveness at scale.
AI-driven cooling optimisation is commercially proven for air-cooled, low-density estates. The technology is still evolving to address high-density servers and hybrid air-liquid cooling for AI factories. In other words the tool works, on the buildings the industry is about to stop building.
Where interconnection is delayed, Siemens supplies modular microgrids as a complete Bridge-to-Grid and Islanded On-Site Power framework, integrating multiple sources with battery storage. Positioned not as backup but as primary deployment, it decouples a data centre’s launch date from the utility’s transmission timeline.
“These elements make the last 20% gap to power datacenter consumption with clean energy too expensive.”
Clean-power PPAs are mostly solar and wind, whose hourly production profile does not match the flat consumption of a data centre. Transmission bottlenecks are a second, non-negotiable constraint. Battery storage and, where available, nuclear are what fill the gap.
As racks push beyond 100 kW, traditional cabling creates thermal choke points and installation delays. Siemens busbar systems are engineered as a power backbone for that density, supporting high-current AC and up to 1,500V and 8,600A DC, which removes AC-to-DC conversion losses and allows hot-swappable rack additions.
A single AI factory draws as much power as an electric arc furnace, an aluminium smelting site, or bulk low-carbon hydrogen production by electrolysis. At interconnection level the differences are minimal. What differs is that inside a data centre the load must be distributed across white space, which is an electrical safety and efficiency problem heavy industry never had.
Hyperscalers are migrating out of the low-latency central clusters toward regions offering large volumes of clean power, immediate grid availability and favourable climate economics: the Nordics and Iberia. France remains a solid option on nuclear access and a high-voltage subsea link to Ireland that opens a route to large volumes of wind.
He is not sure hydrogen will be an option for powering data centres in the next years, but says it is ceasing to be merely a pilot as bulk low-carbon hydrogen from electrolysis is unveiled across Europe and the Middle East. In ten years, at accessible and competitive pricing, it may become an option to fill the clean-power gap. A rare thing in this report: a supplier declining to sell you the future.
Uptime Institute puts the industry average at 1.56, unchanged for a fifth consecutive year, against 2.5 in 2007. Google discloses a fleet-wide 1.09, Meta about 1.08, Microsoft about 1.16. His 10 to 15 per cent overhead describes the disclosed frontier exactly.
DeepMind’s system on Google’s estate achieved a consistent 40 per cent reduction in cooling energy, equal to a 15 per cent cut in overall PUE overhead, and produced the lowest PUE that site had recorded. It is a single-operator result on air-cooled halls, which is the qualification he makes himself.
Google’s own Irish analysis found reaching 90 to 95 per cent carbon-free costs little more than annual matching, but the last few per cent roughly triples the cost using only wind, solar and batteries, because of winter windless spells. Company-wide it reached 66 per cent in 2024, with Singapore at 3 per cent and Oklahoma at 96. His framing is Google’s finding, from the supplier side.
The industry shift is real: NVIDIA has published on 800VDC for the Vera Rubin generation, claiming up to 5 per cent end-to-end efficiency and more than 150 per cent more power through the same copper. But the 1,500V and 8,600A busbar specification is Siemens’ own figure, and no independent laboratory measurement of end-to-end DC gains has been published. Graded as announced, from a supplier describing its own product.
The IEA states that AI-focused data centres can draw as much electricity as power-intensive factories such as aluminium smelters. A 600 kt per year smelter runs near 1 GW continuous at 13 to 15 kWh per kilogram; frontier AI campuses reach hundreds of megawatts to about a gigawatt. The comparison holds at interconnection level, which is the level he makes it at.
Ember projects Nordic and southern European demand growing 110 per cent to 2030 against 55 per cent for FLAP-D, which still holds about 62 per cent of European capacity. The Celtic Interconnector he refers to is real: 700 MW, 575 km, France to Cork, with sources split between energising in 2026 and full commissioning in 2028. It runs both ways, so his point holds in either direction.
The chapter has framed connection as the binding constraint. This contributed brief reads it from inside the utility: why the delay is a digital and process problem, not a physical one, how platformisation compresses connection from years to months without new steel, and what emerging markets actually need to speed approvals. Open any file for the read.
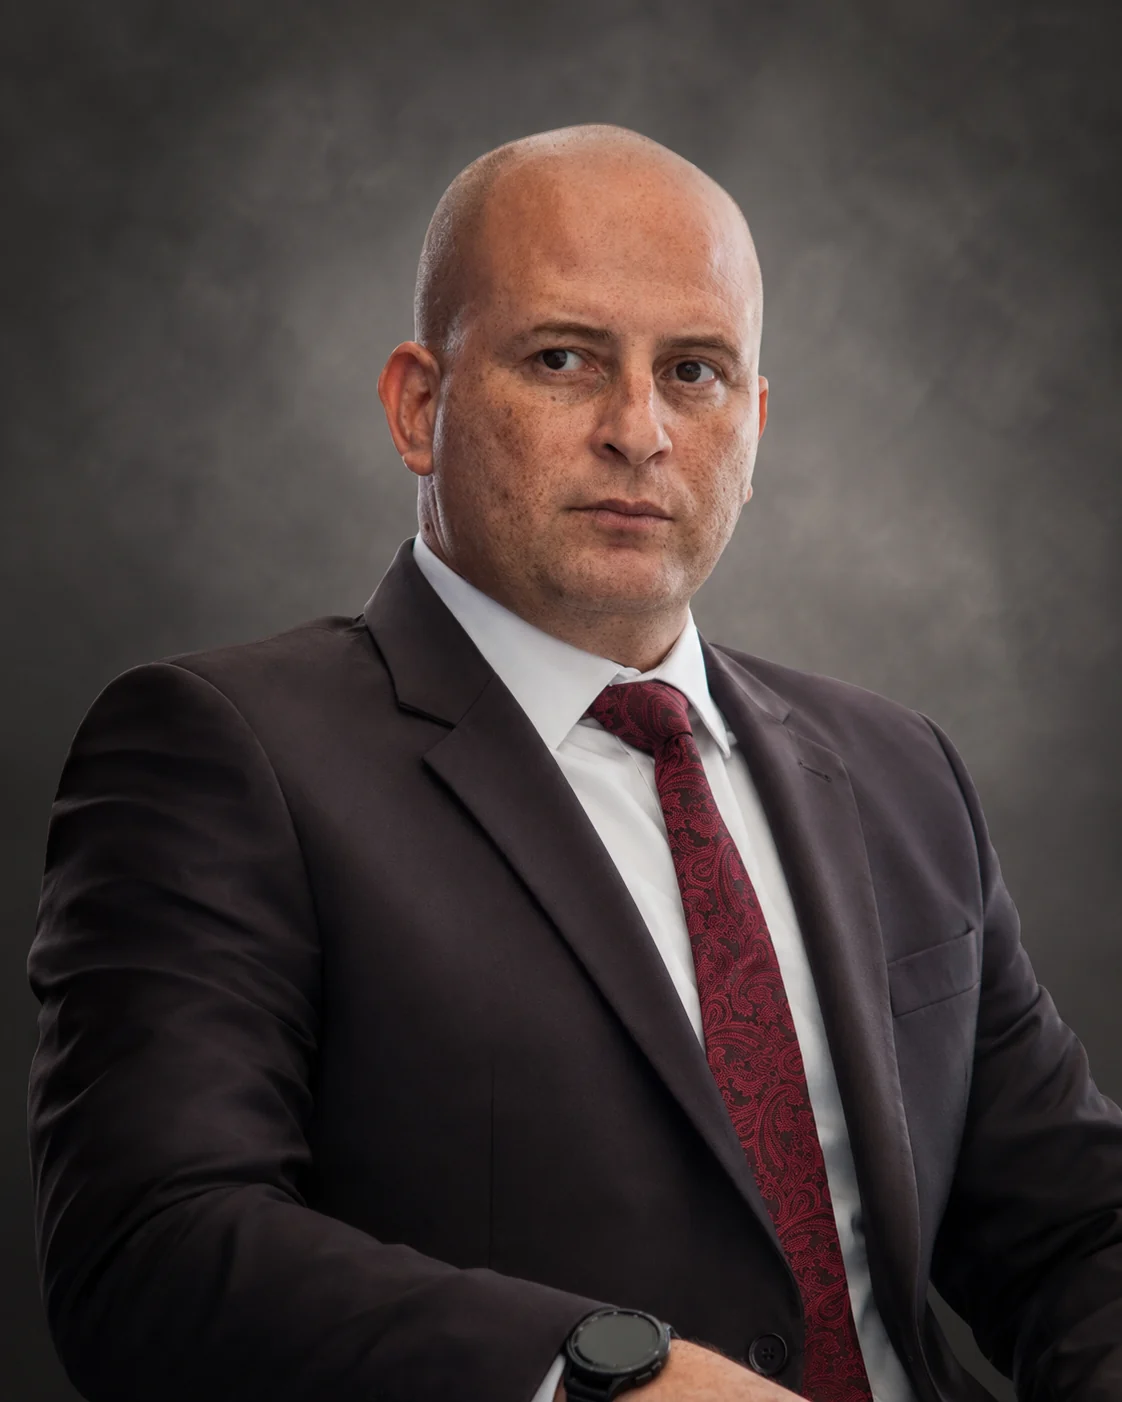
Most reads on the supply chain come from the people selling into it. This one comes from the side that buys. Sanjeev Khanna has spent more than 25 years in global operations, sourcing and supply chain at Oracle and Microsoft, and before that in sales, marketing and business development at Intel, where he ran a P&L in EMEA. At Oracle his teams launched more than 40 cloud regions and more than 100 data centre expansions worldwide; at Microsoft he built the strategic sourcing and supply chain functions for Microsoft Cloud, with more than $7bn a year of spend under management. He began his career as a plant engineer at a 1,100MW power station. Four files here on what is actually scarce, how it is being hedged, and where the cooling line now sits. Four more, where his experience bears on the United States market, sit in the United States chapter.
Twelve operating sites, plotted where the fundamentals actually favour each archetype: one best-fit location and two strong runners-up per workload. Filter by archetype, then open any pin for the analytical case behind it.
The same six dimensions decide every site, but their weight is set by the workload. Choose an archetype below and the conditions, the representative build, the disqualifiers and the scoring weights all re-set. Watch the power bar grow as you move into training, and the connectivity bar grow as you move into inference and edge.
The hard disqualifiers that kill a site before any score is worth running.
The disqualifiers are absolute. A strong score on every other dimension cannot rescue a site that fails one gate. Pick a workload, set the site's conditions, and run it. The site clears a green gate or it stops dead at a red one.
Define the workload. Score the site for it. Apply the gates. Then, and only then, commit the capital.
Where the build actually happens, and what is in the way.