Brazil's real capacity,
not its announced one.

Brazil has the cleanest hyperscale-scale grid in the world and one of the world's tightest water-efficiency thresholds written into tax law. Both could anchor a decade of buildout. Neither has yet produced a financed pipeline at the scale of the announcements.

Installed · end 2025 approx 1,000MW
Announced · 2030 approx 13,200MW
Financed to completion 40-55%
Binding constraint Environmental
licensing
A note from Entelligencia
Brazil in depth, in Enable Brazil.
This chapter runs a little lighter than the others in the report, by design: Brazil is covered in full depth in Enable Brazil. This page sketches the picture; the flagship maps it, operator-by-operator, named interviews, the people of the market. Publishing Q3 2027.
Convenings
New York · May 2027Brazil Week · São Paulo · September 2027

In conversation

The people behind the build.

Interviews and contributed perspectives from across Brazil’s data center industry. Choose a guest to explore their view.

Go deeper with Enable Brazil.
The intelligence environment behind the programme.

Explore Enable Brazil
Analyst overview · 4 Aug 2026

What the Brazil picture actually shows.

The structural advantages are real. The pipeline is not.

Brazil enters 2026 with the cleanest hyperscale-scale grid of any major market, 86.6% renewable in 2025, anchored in hydroelectric capacity that no peer can match. Microsoft and Amazon have committed a combined USD 4.5 billion in cloud-and-AI capex. Lei 15.504/2026 sets an annual cooling-water WUE limit of 0.05 L/kWh for ReDATA eligibility. The country has, on paper, the foundation for the largest renewables-anchored AI infrastructure market in the southern hemisphere.

And yet the regime has taken a year to arrive: the provisional measure lapsed in February 2026, the replacement bill only cleared the Senate on 1 September and became law on 15 September, and implementation still depends on regulatory procedures. The law already fixes the annual cooling-water WUE limit at 0.05 L/kWh; eligibility, evidence and compliance procedures are separate implementation questions. Regime-dependent proposals face that uncertainty. The headline 13.2 GW MME grid-connection queue, repeated across global press as Brazil's 2030 number, is, on Entelligencia's modelling, only 40 to 55 per cent financed to completion. The rest is conditional on incentives, offtake, or capital that has not yet closed.

The thesis for the chapter is this: Brazil's binding constraint is not power, water, capital, or land. It is regulatory clarity, plus transmission from the renewable-rich Northeast to the demand-rich Southeast. The 30 October auction awarded all eight lots across seven states, with an estimated R$8.88bn of investment. Delivery and individual grid connections remain separate milestones. Until both move, the gap between Brazil's announced and delivered capacity will continue to widen, and the operators who actually deliver, verified below, will hold disproportionate market share.

Entelligencia desk · South America · chapter 04 of 10
At a glance · the index

Brazil’s preconditions, scored.

Each spoke is one precondition, scored 0 to 10 for like-for-like reading – indicative editorial weighting, not a published index. Select any spoke or row to read the factor.

From announcement to live MW

Where Brazil's pipeline holds, and where it breaks.

ENT · BRAZIL · THE PIPELINE
The energy pipeline
From announcement to live megawatts.

Clean generation, transmission and the regulatory gate that throttles delivery. Open the pipeline to model where Brazil's queue holds, and where it breaks.

Brazil · May 2026

Pipeline blocked at Permitting. The decree gate is the binding constraint.

Delivered MW
approx 1,000
7.5%
of 13.2K announced
0 3.3K 8.8K 13.2K MEGAWATTS · 2030 ANNOUNCED 01 LAND 02 CLEAN POWER 03 GRID 04 PERMITTING 05 WATER 06 OFFTAKE
GATE 01 Holds
Land
SP, RJ and the Northeast all have available industrial land. Not the binding constraint.
GATE 02 Holds
Clean power
86.6% renewable in 2025 grid. Structural advantage no peer market currently matches.
GATE 03 Conditional
Grid interconnect
SP queue manageable. Northeast→Southeast transmission is the bottleneck.
GATE 04 Partly cleared
Permitting
Lei 15.504/2026 was signed on 15 September. It fixes WUE at 0.05 L/kWh; qualification and compliance procedures depend on regulation.
GATE 05 Conditional
Water / WUE
Annual cooling-water WUE must be at or below 0.05 L/kWh for ReDATA eligibility. The law sets a performance limit, not a named cooling technology.
GATE 06 Conditional
Offtake
Hyperscale capex committed. Site-by-site offtake not yet named.
Analyst read

Brazil's pipeline is not constrained by power, land, or capital. It is constrained by the ReDATA rulebook. The law was signed on 15 September 2026 and fixes the WUE limit; qualification procedures and project delivery remain separate hurdles. Announced capacity is not delivered capacity.

Where it breaks · generation

Brazil has the clean power. The grid cannot carry all of it.

Brazil added around 13.2 GW of solar in 2025 to reach a cumulative 67.1 GW, but the pace is slowing. Regulatory uncertainty, grid-connection barriers for distributed generation and a sharp tariff hike have all bitten: the import duty on solar modules was lifted to 25% just as China cut its export rebate to 9%, raising utility-scale project costs by about 8%. Developers have pulled back, with Trinity Renováveis shelving major projects and ForGreen cutting planned investment by up to 35%.

The harder constraint is the wires. Transmission congestion forced 15 to 20 per cent of solar and wind output to be curtailed in 2025, more than BRL 1.7 billion in uncompensated losses for generators. The regulatory answer is storage: ANEEL has closed a second round of consultations on utility-scale batteries, proposing lower transmission fees and a simpler approval path ahead of a capacity auction, the mechanism meant to soak up curtailed power and firm the grid for the hyperscale loads now queueing for connection.

67.1 GW
Cumulative solar, end 2025
15–20%
Solar and wind curtailed, 2025
BRL 1.7bn
Uncompensated curtailment losses
25%
Solar-module import tariff
Verified and announced · ANEEL, EPE and developer disclosures, 2025 to 2026
The map

Where the power is already waiting.

Brazil’s edge is power: a clean, grid-ready supply that has pulled the densest data-centre cluster in Latin America into the São Paulo southeast, with gigawatt-scale AI cities announced in Rio and the south and a subsea gateway in the northeast. Each glowing node is a real site, colour-coded by what it is: verified live or in build, or an announced megaproject. Open one for the detail, filter by region, and toggle the cables and the renewable grid. The outline follows real national boundary data and every site sits on its true coordinates.

Brazil site map · live
ENT-BR-MAP-2026.06 · 5 hubs plotted
Region
Overlays
Subsea cables
Renewable grid
Verified · live or in build
Announced
Contested · early-stage
SYNAPSE · US–BRAZILMALBEC · BRUSA~12GW GRID-READY · CLEAN POWERSão Paulo metroCampinas · SumaréRio · Elea AI CityFortaleza · TectoScala AI City
Verified · live or in build
Select a site
Tap any site to open its file
Hubs in view
5 hubs
Live load
>120MW
Power posture
Grid-ready, clean
The capacity ledger

Behind the gap: every project in the pipeline, tagged by what's been delivered.

Brazil capacity ledger · live
ENT-BR-LEDGER-2026.06 · 13 of 31 shown
Verified

Independently confirmed. Construction or operation visible on-site or in regulatory filings. Cross-referenced against grid-connection queues, power-purchase filings, and published reporting.

Announced

Press release, no independent confirmation. Project publicly announced but financing-to-completion, permitting, or offtake not yet verified.

Contested

Named source disputes the public figure. A senior operator, regulator, or financier has indicated the announced figure is materially overstated, conditional, or unfinanced.

Status
All Verified Announced Contested
Region
All São Paulo Northeast Multi-site South Rio
8 projects · approx 2,420 MW shown
Project Location Announced Verified live or in build Status Binding constraint
Ascenty SP4 expansion
Digital Realty / Brookfield
Hortolândia, SP
Campinas corridor
68MW
68MW
Verified
Grid interconnect timing
What we verified

Construction visible on-site in publicly available imagery. Power allocation cross-referenced against ONS interconnection record. PPA in place with CPFL for hydro-anchored supply. Tenant migration underway from SP3.

What would change the tag

A material delay on the second 34 MW phase, currently scheduled for Q4 2026, would move that phase to Announced. The verified figure here covers only the first phase.

Sources

ONS interconnection queue · CPFL PPA filings · Reuters · Valor Econômico.

ODATA SP02
Aligned Data Centers
Santana de Parnaíba, SP
São Paulo metro
36MW
36MW
Verified
Water permitting (resolved)
What we verified

Live tenant operation. Closed-loop cooling design indicated in ODATA / Aligned public materials. Targeted to operate below the ReDATA WUE threshold of 0.05 L/kWh.

What would change the tag

Operational. A change in tag would require evidence of off-spec performance or unannounced shutdown.

Sources

ODATA / Aligned press materials · São Paulo state water authority filings · Data Center Dynamics · Reuters.

Elea AI campus, Tamboré
Elea Data Centers
Tamboré, SP
Alphaville corridor
24MW
24MW
Verified
Resolved · liquid-cooled
What we verified

Brazil's first purpose-built AI data centre on liquid cooling. CDU-based deployment delivered by Vertiv. PUE band of 1.15-1.20 referenced in Elea and Vertiv joint materials.

What would change the tag

The flagship Elea facility is live and operating. Future phases are tracked separately and currently sit under Announced.

Sources

Elea + Vertiv joint announcements · Frost & Sullivan 2025 · Data Center Dynamics · Valor Econômico.

Partner case study
Vertiv
The CDU rollout that anchored Brazil's first AI build
Hundreds of coolant distribution units · 100 kW per rack · Frost & Sullivan 2025 LATAM Company of the Year
1.15-1.20
Measured PUE
2024 →
Live, scaling
Read the case →
Microsoft Brazil cloud + AI commitment
Multi-site
SP / RJ, not yet named
$2.7bnCapex
–Not disclosed
Announced
ReDATA implementing decree
Why this is Announced, not Verified

The headline capex figure has been publicly committed but no MW figure has been published by Microsoft for the Brazil deployment, and the deployment timing is partially conditional on ReDATA's implementing decree. The original ReDATA provisional measure expired in February 2026 and was replaced by PL 278/2026, which cleared the Senate on 1 September 2026 and was signed into law on 15 September, with the Ministry of Finance putting the incentive’s draw at up to R$2 trillion of private investment over the decade and R$5.2bn earmarked in the 2026 budget alone. The lapse and the scramble to replace it are why this stays Announced: the incentive is now law, but the regime has already been interrupted once.

What would move it to Verified

A site announcement with named operator partner, grid-interconnection filing, and the ReDATA implementing decree being issued with WUE and clean-power thresholds intact.

Sources

Microsoft press release · Fitch Ratings commentary · ReDATA public consultation documents · Reuters · Bloomberg.

Amazon Brazil cloud + AI commitment
Multi-site
SP-led
$1.8bnCapex
–Not disclosed
Announced
ReDATA implementing decree
Why this is Announced, not Verified

Capex figure committed publicly. No MW disclosure, no site selection disclosure, no operator partner publicly identified for the deployment. Sits behind the same ReDATA policy gate as the Microsoft commitment.

What would move it to Verified

Named site, named operator partner, grid-interconnection filing or evidence of construction.

Sources

AWS Brazil announcement · Reuters · Folha de S.Paulo · Data Center Knowledge.

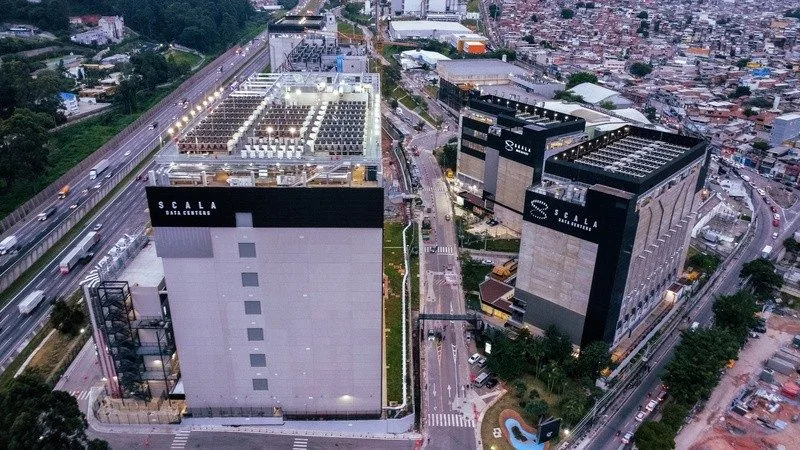
Scala AI City
Scala Data Centers
Eldorado do Sul, RS
Greater Porto Alegre
4,750MW potential
54MW initial
Announced
Enabled; 5 GW grid pathway
Why this is Announced, not Verified

Scala and the Rio Grande do Sul government disclosed an initial US$500 million / R$3 billion investment, with 54 MW of initial IT capacity in Eldorado do Sul and expansion potential to 4.75 GW across more than 1,730 acres. The local enabling law was sanctioned in December 2024, and in May 2025 the Ministry of Mines and Energy recognised a technical solution for a 5 GW grid connection. Enabled and in development, with no operating phase or named anchor customer in the public record.

What would move the campus figure to Verified

A named anchor tenant, grid-interconnection energisation and an operating first phase. Separately, Scala's Tamboré buildings in Barueri, SP (SGRUTB09 to 11, about 84 MW) are under construction within a wider 900 MW-plus Scala programme.

Sources

Scala and Rio Grande do Sul government announcements · Ministry of Mines and Energy · ONS queue filings · Valor Econômico.

ODATA SP04
Aligned Data Centers
Osasco, SP
Greater São Paulo
48MW
48MW
Verified
Live, early 2025
What we verified

Announced March 2025 and described by ODATA as operational from early 2025. Investment of more than US$450 million, with the total campus put at R$2.6 billion in later technical material. ODATA's second verified Brazilian site after SP02, carrying the same closed-loop cooling and sustainability framing.

What would change the tag

Operational. A change would require evidence of off-spec performance or an unannounced shutdown. No anchor tenant is publicly named.

Sources

ODATA / Aligned press materials · Data Center Dynamics · Reuters.

Ascenty AI hyperscale wave
Digital Realty / Brookfield
Campinas region, SP
Sumaré, Vinhedo, São Paulo
150MW pre-leased
SPO05live
Announced
Pre-leased; phased to 2027
Why this is Announced, not Verified

In May 2026 Ascenty said it had signed 150 MW of new AI contracts with global hyperscalers, fully pre-leased on a long-term basis, supporting four new hyperscale data centres across Sumaré and Vinhedo plus a sixth São Paulo site. SPO05 has entered operation and SPO06 is under construction for May 2027. The clearest pre-leased hyperscaler-demand signal among the named operators, though customer names are not disclosed and most of the capacity is not yet energised.

What would move it to Verified

Energisation of the named Sumaré and Vinhedo phases, with grid-interconnection evidence beyond the live SPO05 building.

Sources

Ascenty May 2026 announcements · Digital Realty disclosures · Data Center Dynamics.

Elea Rio AI City
Elea Data Centers
Rio de Janeiro
Olympic Park region
1,500MW phase 1
approx 80MW in build
Announced
Phased; 300 MW+ power secured
Why this is Announced, not Verified

Announced May 2025. RJO1 is operating and RJO2, about 80 MW, is under construction for 2026, with RJO3 and RJO4 adding a further 120 MW. First-phase target 1.5 GW, long-term potential 3.2 GW. Elea's April 2026 transaction, I Squared Capital's majority-stake acquisition, cited more than 300 MW on land with secured power and more than 1 GW planned. Separately, Elea won a named anchor: the Petrobras supercomputing data centre, 30 MVA on a 17-year, R$2.3 billion contract.

What would move it to Verified

Energisation of RJO2 and a named hyperscaler anchor for the AI City itself, distinct from the Petrobras HPC contract.

Sources

Elea announcements (May 2025, Apr 2026) · Petrobras procurement · Data Center Dynamics.

Takoda dual-campus
Takoda / TIVIT
Sumaré, SP + Barra, RJ
Multi-site
160MW
36MW phase 1
Announced
RFS Q3 2027
Why this is Announced, not Verified

Takoda, the data-centre company TIVIT spun out in 2023, markets two hyperscale AI and GPU campuses: Sumaré, São Paulo at 96 MW and Barra, Rio de Janeiro at 64 MW, 160 MW in total. Phase 1 is 18 MW per campus, with ready-for-service in Q3 2027. Takoda says land, permits, critical-equipment contracts and construction contracts are already in force, but no customer is named.

What would move it to Verified

Start of construction with grid-interconnection evidence and a named anchor tenant.

Sources

Takoda 2026 project pages · TIVIT corporate materials.

Tecto TGRU1
Tecto / V.tal
Santana de Parnaíba, SP
São Paulo metro
200MW
–in build
Announced
Part of US$2bn plan to 2028
Why this is Announced, not Verified

Tecto, V.tal's data-centre platform, lists TGRU1 in Santana de Parnaíba as under construction for high-density AI and hyperscale loads, up to 200 MW, part of a wider US$2 billion investment plan through 2028. Tecto also markets TPOA1 in Porto Alegre, RS, 20 MW with a first phase in Q4 2026 tied to the Malbec subsea cable, and TFOR3 in Fortaleza. The platform runs on certified renewable energy; no anchor is named.

What would move it to Verified

Energisation, grid-interconnection evidence and a named tenant for TGRU1.

Sources

Tecto / V.tal site and announcements · Reuters · Data Center Dynamics.

Northeast AI corridor (composite)
Multiple announced operators
Ceará / Pernambuco / RN
Cable-landing corridor
approx 3,200MW
approx 40MW
Contested
Offtake + transmission
Why this is Contested

Aggregate announced capacity across the Northeast corridor exceeds three gigawatts. Cross-referenced against MME grid-queue filings and named financing, Entelligencia assesses a significant share of these announcements as materially overstated or unfinanced. Transmission capacity from the renewable-rich Northeast to demand centres in the Southeast has not been built at the scale required.

What would change the tag

Named transmission build-out commitments by ONS / MME, plus offtake agreements for specific named operators in the corridor.

Sources

MME grid-queue analysis · Reuters · Financial Times · Valor Econômico · Entelligencia cross-reference against publicly named projects.

Aggregate "2030 hyperscale pipeline"
Industry body composite
Brazil-wide
All regions
approx 13,200MW
approx 1,000MW today
Contested
Composite
Why this is Contested

The 13.2 GW figure is the MME grid-connection request pipeline, repeated in media as "Brazil's 2030 capacity". The Entelligencia view, cross-referenced with the named advisory council, is that 40 to 55 per cent of that pipeline is currently financed to completion. The rest is conditional on incentives, offtake or capital that has not yet closed.

What would change the tag

Operational qualification procedures under Lei 15.504/2026, plus named offtake and financing that move the modelled financed share above 70%.

Sources

MME grid queue · ANEEL filings · Entelligencia aggregation · Reuters · Valor Econômico · Bloomberg.

Last verified · 12 May 2026 · 8 of 31 tracked projects shown
The file

Six findings behind the gap.

Findings dossier · BRA
Compiled May 2026
Verified Announced Contested
Exhibitsthree campuses behind the headline numbers
The TikTok and Casa dos Ventos campus at Pecem, Ceara
EXHIBIT A · CEARATikTok and Casa dos Ventos, PecemHeadline USD 37.7 billion, 300 to 900 MW, wind-powered, targeted 2027.
The Scala AI City campus at Eldorado do Sul
EXHIBIT B · RIO GRANDE DO SULScala AI City, Eldorado do SulA 5 GW grid authorisation, one of the largest ever issued in Brazil.
The Tambore campus at Barueri, Sao Paulo
EXHIBIT C · SAO PAULOTambore campus, BarueriAt 450 MW IT capacity, the largest campus in Latin America.
The document

The paper trail, annotated.

Three primary sources behind Brazil’s build: the tax regime, the energy signal and the grid queue, each graded claim by claim against the record. Select a tab to bring a document forward, an underlined claim to read the analysis, or filter by grade.

Source ·   · marked by Entelligencia
Filter
The people

Who actually decides Brazil's data-centre buildout.

Eduardo Zago de Carvalho
Managing Director, LATAM · Equinix
Profile · 01 of 05
Eduardo Zago de Carvalho
Managing Director, Latin America · Equinix
Influence
Interconnection, ecosystem growth, LATAM expansion. 8 Brazilian DCs, a 9th in pipeline, 5 more properties acquired.
Working on
Land pipeline, tax reform as AI catalyst, hyperscale + edge + retail.
Brazil is priority region. Plenty of space and financial resources.
Reuters · Oct 2025
Christopher Torto
Founder & CEO · Ascenty
Profile · 02 of 05
Christopher Torto
Founder & CEO · Ascenty
Influence
38 LATAM data centres operating, in build or development. 750+ customers. The signature LATAM build-out story.
Working on
Disciplined scaling, AI-led demand, 100% SLA culture. View: $1bn+ deals are now the norm in Brazil.
Grow with discipline, deliver at scale, move infrastructure forward in LATAM.
The Tech Capital · 2025
Ricardo Alário
CEO · ODATA, an Aligned company
Profile · 03 of 05
Ricardo Alário
CEO · ODATA, an Aligned Data Centers company
Influence
DC SP04 Osasco: 48 MW, USD 450M, first Delta³ cooling in Brazil. 100% renewable across BR sites.
Working on
Post-Aligned integration. AI/HPC density. Land-and-power-first across the Americas.
Speed-to-market at a velocity otherwise unknown in our business.
Aligned announcement · 2024
Alex Sasaki
VP, Latin America · Vertiv
Open the voice
Profile · 04 of 05
Alex Sasaki
Vice President, Latin America · Vertiv
Influence
The enabling infrastructure layer. Frost & Sullivan 2025 LATAM Company of the Year, AI & HPC.
Working on
Scalable power and cooling for AI density. Liquid-cooled deployment economics. LATAM ecosystem.
Brazil is at a turning point to become a global data center hub.
GRI Institute · Oct 2025
João Borges
Founder & CEO · Nexus Telecom Brasil
Open the voice
Profile · 05 of 05
João Borges
Founder & CEO · Nexus Telecom Brasil
Influence
The passive layer the build depends on. A tower company managing ~150 sites, ~20 a month, anchored by Vivo, riding 5G coverage targets.
Working on
Converging power, fibre, towers and edge into one platform. Disciplined, demand-led growth over speculative capex.
Demand for data centres is growing faster than the connectivity and energy to support it.
Contributor · The Next Hotspot · 2026

The Brazilian build, in their words

In conversation · operators and the industry body

Contributions gathered through the report’s open call. Named voices appear with consent; the hyperscaler operator is verified and held on file at their request.

The supply chain

From capital to compute · who’s active in Brazil

Brazil supply chain · live
Hover any node · Click for detail
Investors
Brookfield
KKR
GIC
Patria
BTG
DigitalBridge
BNDES
Suppliers
Vertiv
NVIDIA
Schneider Electric
ABB
Cummins
Trane
Caterpillar
DPR Construction
Operators
Ascenty
ODATA
Scala
Elea
Tecto
Equinix
Hyperscalers
Microsoft
AWS
Google
Oracle
Meta
IBM
Corporates
Itaú
Bradesco
Nubank
Petrobras
Vale
Mercado Libre
Magazine Luiza
AI workloads
OpenAI
Anthropic
Mistral
Cohere
Stability AI
xAI
Flow

Capital flows left to right, from investors through suppliers and operators to the hyperscalers, corporates and AI workloads that consume the stack. Hover any node to trace its position. Click for the company brief.

06 tiers · 41 entities
The wider programme

More in Enable Brazil.

Brazil is one chapter. The flagship publishes Q3 2027, with four quarterly briefings and three convenings between now and then.
Preview of the Enable Brazil intelligence environment

There’s a bigger
picture of Brazil.

Explore the projects, power, policy and people behind the build in our AI-enabled intelligence environment.

Explore Enable Brazil

Free and sponsor-supported. Sign in with your invited work email, or request VIP access in the app.

Supported byVertivOracle3M