Sociogencia · the politics of the build

The data centre midterm elections.

It arrived in the post. A grid auction nobody watched put data centres on household bills, and then on the ballot.

The read

Not a forecast. One Virginia seat has already turned on it, and every figure here is graded.

AuthorAdam Roberts
SubjectThe ratepayer revolt
Vote3 November
LensWho pays for the grid
Analyst overview · 30 Sep 2026

The industry lost the argument it never turned up to.

Two years ago the price of capacity on the largest grid in America was a wholesale number that almost no household had heard of. It is now a campaign position in at least four states, a statewide permitting moratorium in one, and a live question on the ballot of the one elected utility commission where the buildout is the campaign.

The mechanism is not complicated and it is not really about data centres. An auction cleared at its ceiling three times running. The cost landed in sixty-five million letterboxes. People who had never used the phrase interconnection queue went looking for something to blame, and found the largest new thing on their grid.

The industry did not lose a debate. It was absent from one. Through the whole of 2025 the sector argued about power procurement and chip supply while the political cost of its own load was being priced by county boards, delegate races and a governor’s campaign. By the time it noticed, the position was set.

What follows is not a forecast. Virginia has already happened, Georgia is measurable, New York is signed. The case reads the record, grades every claim on it, and stops short of predicting November.

10×
Rise in PJM capacity prices across two auctions, the number the anger is made of
$6.2bn
Of the $6.5bn assigned to data centres in the December 2025 auction, for capacity that has not been built
636
Votes that decided the one Virginia seat fought on data centres alone
1 of 50
States with a statewide moratorium in force. The rest of the map is local
Entelligencia desk · Sociogencia · Case 09 · 26 graded claims

A first-time candidate, one issue, and a seat nobody expected to move

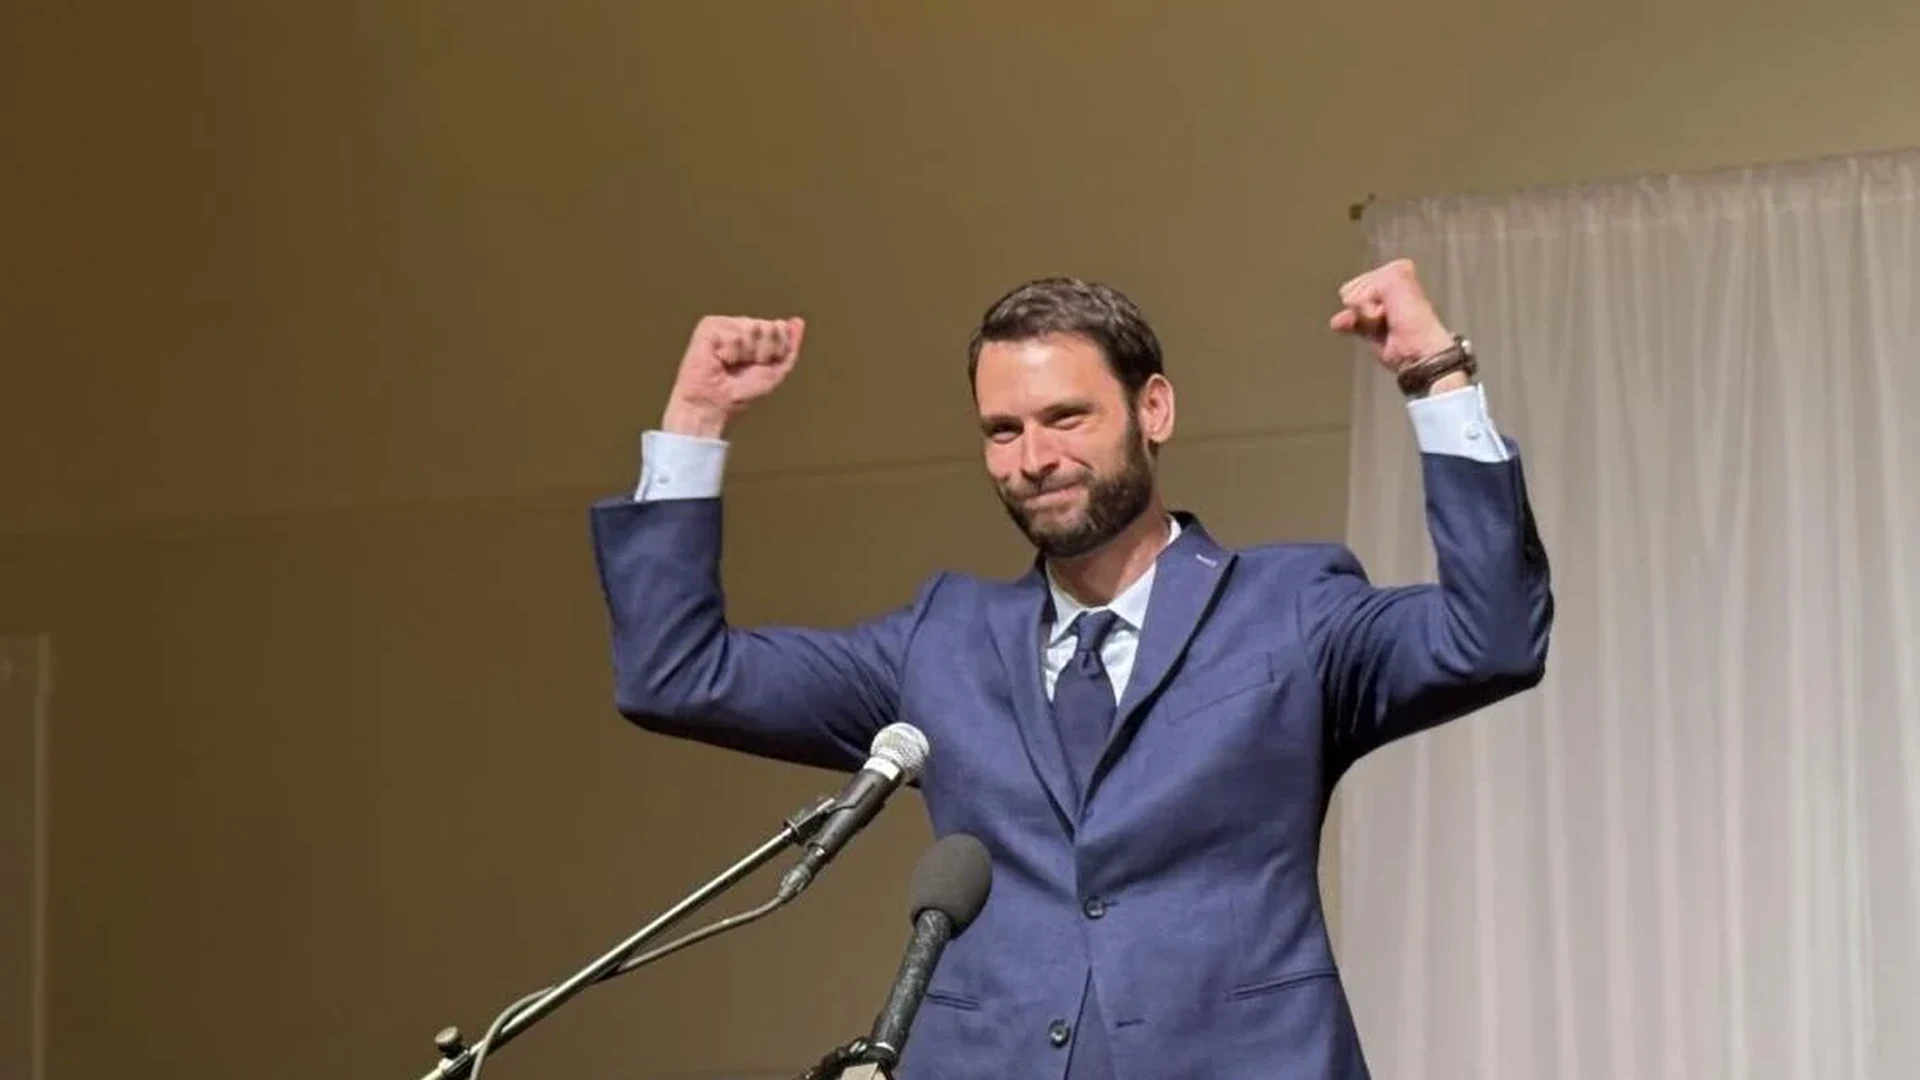
In November 2025, John McAuliff flipped a Loudoun and Fauquier seat in the Virginia House of Delegates that had been Republican for decades. He did it on a single subject: what data centres were doing to his constituents’ electricity bills. He built a website named after his opponent’s ties to the industry and called it Data Center Geary. He won by 636 votes, 50.6 to 49.2, outspending his opponent roughly three million dollars to eight hundred and fifty thousand. Verified

That is the thesis in one district. The most boring infrastructure story in America, the allocation of grid upgrade costs, turned out to be the sharpest instrument on the ballot.

John McAuliff celebrating his win
636
votes, the winning margin
50.6
per cent, against 49.2
$3m
spent, roughly, against $850,000
November 2025Virginia House of Delegates, a Loudoun and Fauquier seat

The map the permits made

A year ago there was no map to draw. Now there is one statewide instrument in force, one statewide audit, one state that priced the load rather than pausing it, one that passed a pause and could not keep it, and local instruments across most of the rest. The trackers do not agree on how many. Good Jobs First counts at least twelve states with filed moratorium bills. One survey documents 533 local instruments across 42 states, another 242 across 36, another 225 across 30 of which 151 are in force. Those are four definitions of the same phenomenon, and the disagreement is the most honest figure on this page.

Moratorium tracker · state instruments

Where the permits stopped

One tile per state and the District of Columbia, equal weight to each, so a count of instruments is not drowned out by land area. Colour marks the strongest instrument recorded. Filter by instrument, search, or select a state to read its file.

Verified where an instrument is named and dated; Contested on the totals, because the trackers count differently. Compiled from Good Jobs First, the Moratorium Nation survey current to 19 August 2026, and two state-level trackers. One tile per state and DC, equal weight to each, not a population or capacity cartogram. Local instruments are recorded at city and county level and change weekly.

The number the anger is made of

PJM is the grid under Virginia, Maryland, New Jersey, Pennsylvania, Ohio and eight other states: around sixty-five million customers. Its capacity auction sets what everyone pays to guarantee power is there when needed. In two years that price went from $28.92 per megawatt-day to the regulator’s own ceiling, and it has cleared at that ceiling three times running since.

Swipe for all five auctions →

Scroll the chart →
Three of these five auctions did not clear at a market price. They cleared at the regulator’s ceiling, marked on the chart. One market monitor gives the four answers on the left, and they are not rival methods. They are different denominators. Select one to see what was measured, or select any bar for that auction’s file.
Sources · PJM Base Residual Auction reports, Monitoring Analytics, Utility Dive. Contested

One monitor. Six numbers

Almost every figure in this argument traces to a single body: Monitoring Analytics, PJM’s independent market monitor. It has no rule-making power and no enforcement power. Its influence is entirely in being believed, and both sides of this election quote it. Filter by grade to see which of its numbers are checkable and which are the monitor’s own claim about a market it monitors.

Cost monitor · live file as of August 2026
All six Verified Contested
Contested

The denominator swap

63per cent, against 40

The two figures quoted against each other in this argument come from the same place. Both are Monitoring Analytics, PJM’s own independent market monitor. They are not rival methods reaching different answers; they are answers to different questions. Sixty-three per cent is a share of the increase in one auction. Forty is a share of the total cost of another. Quoting one against the other is not a dispute. It is a denominator swap, and it is the most common error in the coverage.

Source · Monitoring Analytics · the same monitor, two questions
Verified

Paid for, not built

6.2$bn of $6.5bn

The number inside the number, and the one that should be on a leaflet. Of the $6.5bn the monitor assigns to data centres in the December 2025 auction, $6.2bn is for data centres that have not been built. Households are paying now to hold capacity against facilities that may never arrive, and nothing is refunded if they do not.

Source · Monitoring Analytics · December 2025 auction
Verified

This year, so far

9per cent of the wholesale price

Existing and forecast data centre load made up 9 per cent of the wholesale price of power in PJM through July 2026, at $10.48 per MWh, and that is via the capacity market alone. It does not include data centre effects on the price of electricity itself or on transmission.

Source · Monitoring Analytics · 2026 first-half state of the market
Verified

The year the cost moved

54per cent in one year

PJM wholesale power costs rose 54 per cent in a single year. Three consecutive auctions have now cleared at the regulatory ceiling rather than at a price, the last two of them short of the reliability target. The July 2026 auction cleared close to 7 GW below target and drew roughly 500 MW of new supply.

Source · PJM · FERC chairman’s remarks, July 2026
Contested

The widest claim

46per cent, $29.4bn of $63.6bn

Across four auctions the monitor puts data-centre-driven charges at $29.4bn of $63.6bn. It has not published the method, and PJM has not endorsed the split. It should be read as a claim by the market monitor about a market it monitors, which is why it is the widest figure in this case and the softest.

Source · Monitoring Analytics · method unpublished
Verified

What is not disputed

3auctions at the ceiling

The load is real, it is new, and it arrived faster than the grid could price it. That much is agreed by every party to this argument, including the ones who disagree about everything else on this page.

Source · PJM auction results · public record
Four of the six are checkable against published auction results · two are the monitor’s own attribution and are graded Contested for that reason
The 46 per cent figure carries no published method · PJM has not endorsed it
The escalation

How a wholesale price became
a ballot question.

Every date in this sequence is verified elsewhere in this case. Put in order they are one story: a number that lived in an auction nobody watched, arriving on household bills, then in a county zoning meeting, then in a delegate race, then a governor’s race, then an executive order, and now on a ballot. Three years, from a spreadsheet to a campaign position.

Seven scenes · scroll and click to explore
01/ 07
2023
A price nobody was watching
The auction sets what sixty-five million customers pay to guarantee power is there when needed.
$28.92The baseline
2024
The auction breaks
Wholesale power costs in PJM later rise 54 per cent in a single year.
9.3xThe jump
2025
The first county says no
Four surveys give four counts. That disagreement is on the map later in this case.
HundredsLocal pauses
November 2025
One issue, one seat
He named his website after his opponent’s ties to the industry.
50.6%The flip
November 2025
The state follows
The wave the issue rode in on. It is not a forecast.
23.3 ptsStatewide
July 2026
A state stops issuing permits
Texas orders an audit instead. Virginia prices the load rather than pausing it. Maine passes a pause and loses it to a veto.
EO 62First statewide
November 2026
The question on the ballot
None of the bodies that set that price are on any ballot. That is File 04, below.
3 NovOn the ballot
2023 · A price nobody was watching
2023 · Scene 01 / 07

A price nobody was watching

PJM’s capacity auction clears at $28.92 per megawatt-day. It is a wholesale number in a market almost no household has heard of, and it is about to stop being one.

2024 · Scene 02 / 07

The auction breaks

The 2025/26 auction clears at $269.92 per megawatt-day, more than nine times the year before. The next three clear at the regulator’s own ceiling, the last two short of the reliability target. Households start to find it on their bills.

2025 · Scene 03 / 07

The first county says no

Local pauses begin appearing across the country. What starts as a zoning argument in a handful of counties becomes, within eighteen months, hundreds of local instruments across most states. The trackers still do not agree on how many.

November 2025 · Scene 04 / 07

One issue, one seat

John McAuliff flips a Loudoun and Fauquier seat held by Republicans for decades, running on a single subject: what data centres were doing to his constituents’ electricity bills. 50.6 to 49.2, outspent roughly three to one.

November 2025 · Scene 05 / 07

The state follows

Abigail Spanberger wins Virginia 57.6 to 42.2, having pledged the industry would pay its fair share. Every county and city moves at least 4.7 points. In Spotsylvania, the largest swing in the state, 23.3 points. On 18 September 2026 she signs Executive Order 22: no non-disclosure agreements for state agencies, stricter noise, water and emissions standards, and a review of diesel backup. Ending by-right approval above 25MW goes to the legislature in January. It is not a moratorium, and campaigners who wanted one say it does not go far enough.

July 2026 · Scene 06 / 07

A state stops issuing permits

New York becomes the first state to stop issuing them. Executive Order 62, signed 14 July, holds state environmental permits for data centres drawing 50 megawatts or more in abeyance for up to a year. It is signed five months before a governor faces the voters.

November 2026 · Scene 07 / 07

The question on the ballot

Nominees in Ohio and Florida now run on a moratorium or a pause. In Wisconsin the moratorium candidate lost her primary by half a point, and the fault line runs inside the Democratic party rather than between the parties. Two Georgia Public Service Commission seats are up. A wholesale price from 2023 is now a campaign position.

The files

Five fights, opened when you want them.

The sequence above is the argument. What follows is the evidence behind it, kept closed so the case reads in one sitting. Open any file and it expands in place. Everything is still here, and still graded.

The read

It is an affordability election

Adam Roberts
Entelligencia · Adam Roberts

Nearly half of Americans expect data-centre energy costs to be a campaign issue, and Pew finds 38 per cent think the effect on their bills is mostly bad against 6 per cent who think it is good. Those are not the numbers of a movement. They are the numbers of a grievance, and grievances attach to whatever is nearest when the bill arrives. By September four national polls put opposition to a data centre in the respondent’s own community at 65 to 71 per cent, while fewer than 1 per cent of voters in the NYT/Siena poll named it their top issue.

What the record shows is narrower, and more useful. A wholesale price became a household cost, a household cost became a county instrument, a county instrument became a delegate race, and a delegate race became a governorship. Three years, from a spreadsheet to a campaign position, with no national campaign, no organising body and no single opponent.

Analysts at Jefferies put the finding plainly: every 2026 candidate will be forced to take a position on data centres, for or against. That is the real result. Not that the industry loses, but that it has lost the ability to be invisible, and it lost it in a single cycle.

The bodies that actually set the price are still not on any ballot. FERC, PJM, the market monitor and the reliability regulator will decide more about American electricity bills over the next four years than any of the races in this case. Georgia is the exception, and it is the exception precisely because someone can be voted out.

The question
Not whether the industry can win these votes. Why it is on the ballot at all.

Three years after nobody outside the sector could name a capacity auction, a wholesale price is a campaign position in at least four states, a statewide permitting moratorium in one, and a live question on the ballot of an elected utility commission.

Sociogencia · Case 09 · twelve sections, every figure carrying its evidence grade and its source at field level · compiled August 2026, Georgia races and moratorium tracker verified 11 September 2026, Virginia updated 24 September 2026, polling, Texas and Data Center Watch updated 30 September 2026 · totals graded Contested where trackers count differently · this case reads a record and does not forecast

The Next Hotspot · dropping
Entelligencia

Two elections read. The cost is next.

The Data Centre Midterm Elections is a Sociogencia case inside The Next Hotspot, an interactive read on where the world actually builds AI infrastructure. The full edition is live, and the remaining drops are dated below.

Live now · SociogenciaOriginal analysis is dropping already. Read the studies.Read the studies →

Get each drop as it lands
One email per release: original analysis, the market chapters, the full report. No noise.

EntelligenciaThe Next Hotspot